


From ceasefires to blockades, the world continues to feel increasingly unpredictable. Headlines remain dominated by conflict in the Middle East, rising geopolitical tension and markets reacting in real time. When the world feels uncertain, people naturally ask one question: Should I stay, or should I go?
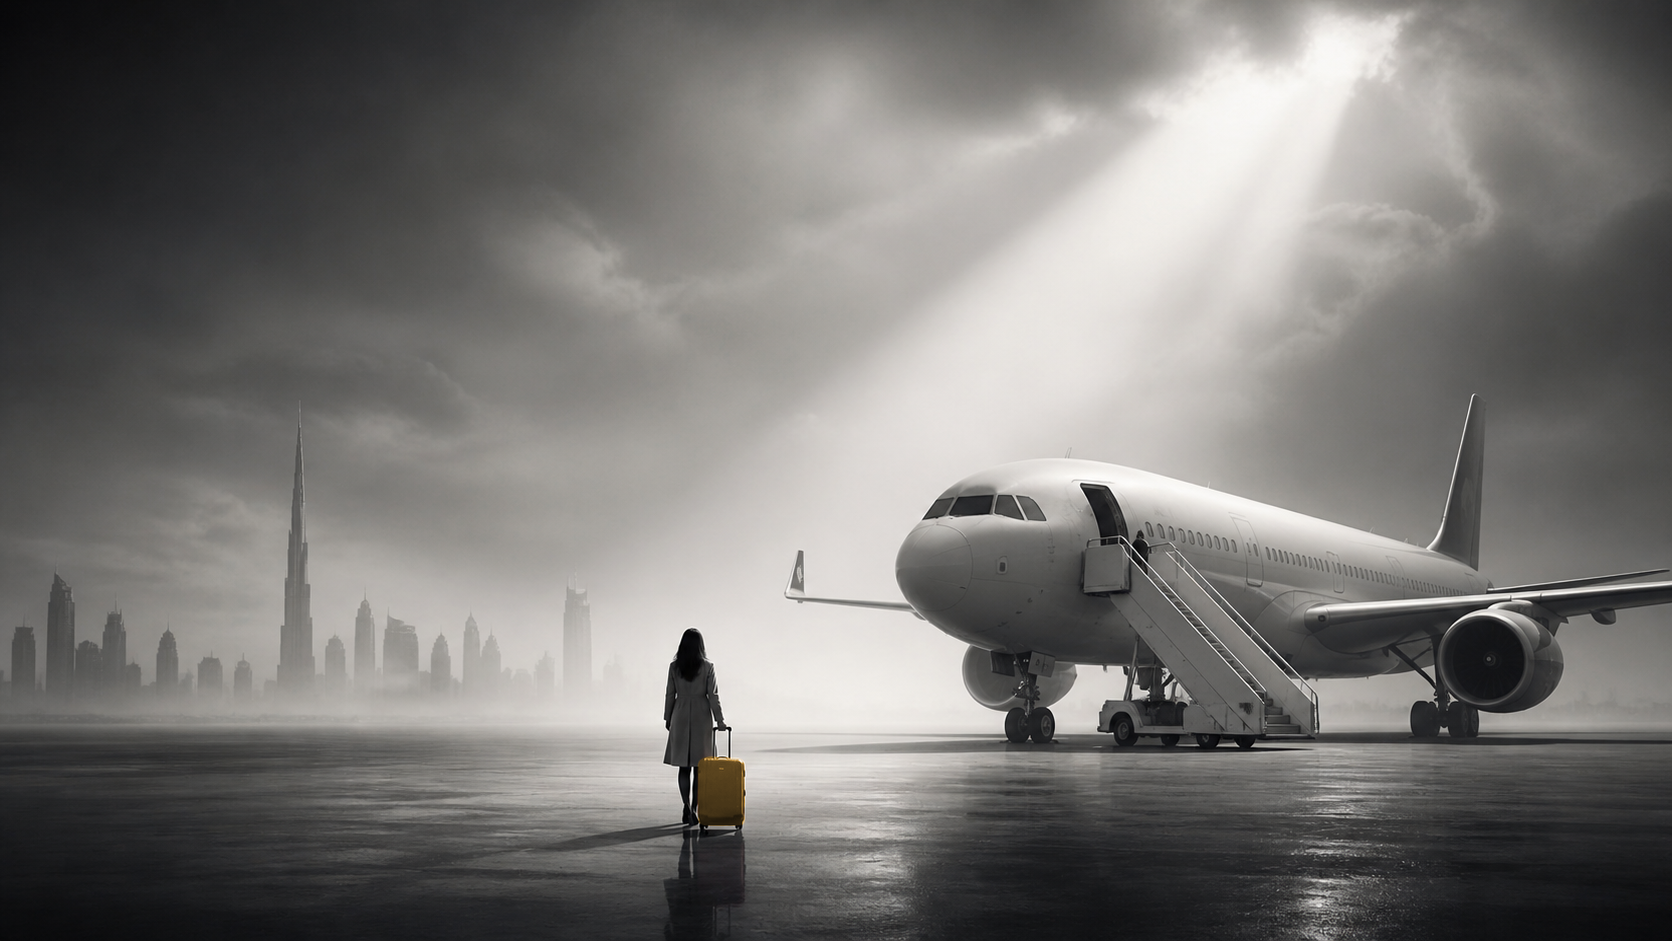
A recent story reported across several global publications about Australian ‘ghost flights’ prompted reflection on behavioural tendencies during crises. The reports focused on repatriation flights from the UAE during the current Gulf conflict. Planes designed to carry nearly 500 passengers initially experienced a surge in demand. However, many later departed with fewer than 100 passengers on board.
According to the reports, rows of empty seats frustrated the Australian Government, which had introduced the repatriation service.
The UAE’s ‘ghost flights’ and human behaviour
Why had people stopped leaving? Why did they no longer take the opportunity to “get to safety”?
What stood out most about the UAE’s ‘ghost flights’ was the reaction from those who stayed behind. Despite the uncertainty, many residents chose not to flee. Instead, they trusted government information, believed they remained safe and still felt at home. This raises an important question. Why would people make completely different decisions despite facing identical headlines, risks and information?
Some individuals reacted to the noise. Others responded based on trust. They trusted their environment, the systems surrounding them and the people advising them. More importantly, they understood the difference between what was genuinely true and what was simply loud.
Financial decisions mirror crisis behaviour
This same pattern often appears in financial decision-making. When markets fall and uncertainty rises, people must decide whether to react emotionally or respond strategically. In many ways, the UAE’s ‘ghost flights’ mirror how investors behave during volatile periods. Do you “board the plane”, or do you stay the course?
In these moments, intelligence and access to information rarely determine outcomes. Instead, trust becomes the defining factor. People need someone who helps them interpret the noise, communicates clearly, prioritises their best interests and brings them back to the plan.
This is where financial empowerment truly begins. Financial confidence does not come only from building wealth. It also comes from making informed decisions during uncertainty. People should not feel driven by fear or paralysed by complexity. Rather, they should feel grounded because they understand their financial strategy and trust the person guiding them.
Financial planning is about preparedness
Financial planning is not about predicting the next crisis. Instead, it ensures that when the world feels unstable, you do not need to make reactive decisions because a plan already exists.
According to a study by Vanguard Group, a wealth manager can add approximately 3% per year in net returns after fees. Importantly, this value does not primarily come from stock picking. Instead, the study found that behavioural guidance generates most of the additional value.
In today’s volatile environment, a goals-based approach to wealth management creates clarity, confidence and calm. A wealth manager should act as the chief financial officer of the family. This role ensures that all aspects of wealth receive proper attention. The first step involves identifying goals across three tiers of importance.
The first tier focuses on security. This practical discussion covers retirement essentials such as food, housing, medical aid and basic living expenses during later life. In addition, conversations should include goals like children’s education.
The second tier centres on joy. These goals often include travel and hobbies. However, they also involve the comfort people feel when loved ones remain financially secure after their passing. Legacy planning and philanthropy, therefore, fall into this category.
The final tier involves bucket-list ambitions. Financial planning should not act as a constraint. Instead, it should enable people to dream. Discussing aspirational goals with a wealth advisor helps turn long-term ambitions into practical plans.
Once these goals are mapped out, wealth managers collaborate with specialists to develop a holistic financial strategy. This process incorporates expertise in tax, investment management, fiduciary services and risk management. Together, these disciplines create a robust financial blueprint for individuals and families.
Importantly, financial plans should never remain static. Circumstances evolve, and plans should evolve accordingly. Therefore, advisors should schedule regular reviews to ensure strategies remain aligned with changing life circumstances.
Trust and clarity matter most
The value of advice does not increase in a straight line. Instead, its greatest impact often appears during moments of crisis. During these periods, advisors can preserve significant portfolio value by preventing poor decisions. Consequently, communication becomes just as important as technical expertise. However, many people still judge financial advisors based on how intelligent they sound or whether they work for large firms. In reality, these factors rarely build long-term confidence.
Nearly half the value of financial advice is non-technical. Instead, it rests on trust, emotional reassurance, and clarity. Clients need to feel comfortable asking difficult questions. They also need advisors who listen carefully and explain complex matters clearly.
 Most importantly, clients must feel safe enough to remain completely honest. Financial discussions involve deeply personal information and important decisions. People often navigate these conversations during periods of uncertainty, change or fear.
Ultimately, moments like the UAE’s ‘ghost flights’ reveal something fundamental about human behaviour. In periods of panic, people do not seek someone who merely impresses them. They seek someone who can guide them and help answer the enduring question: Do I stay or do I go?
Nicola Langridge | Financial Planner | Private Client Holdings | mail me |