


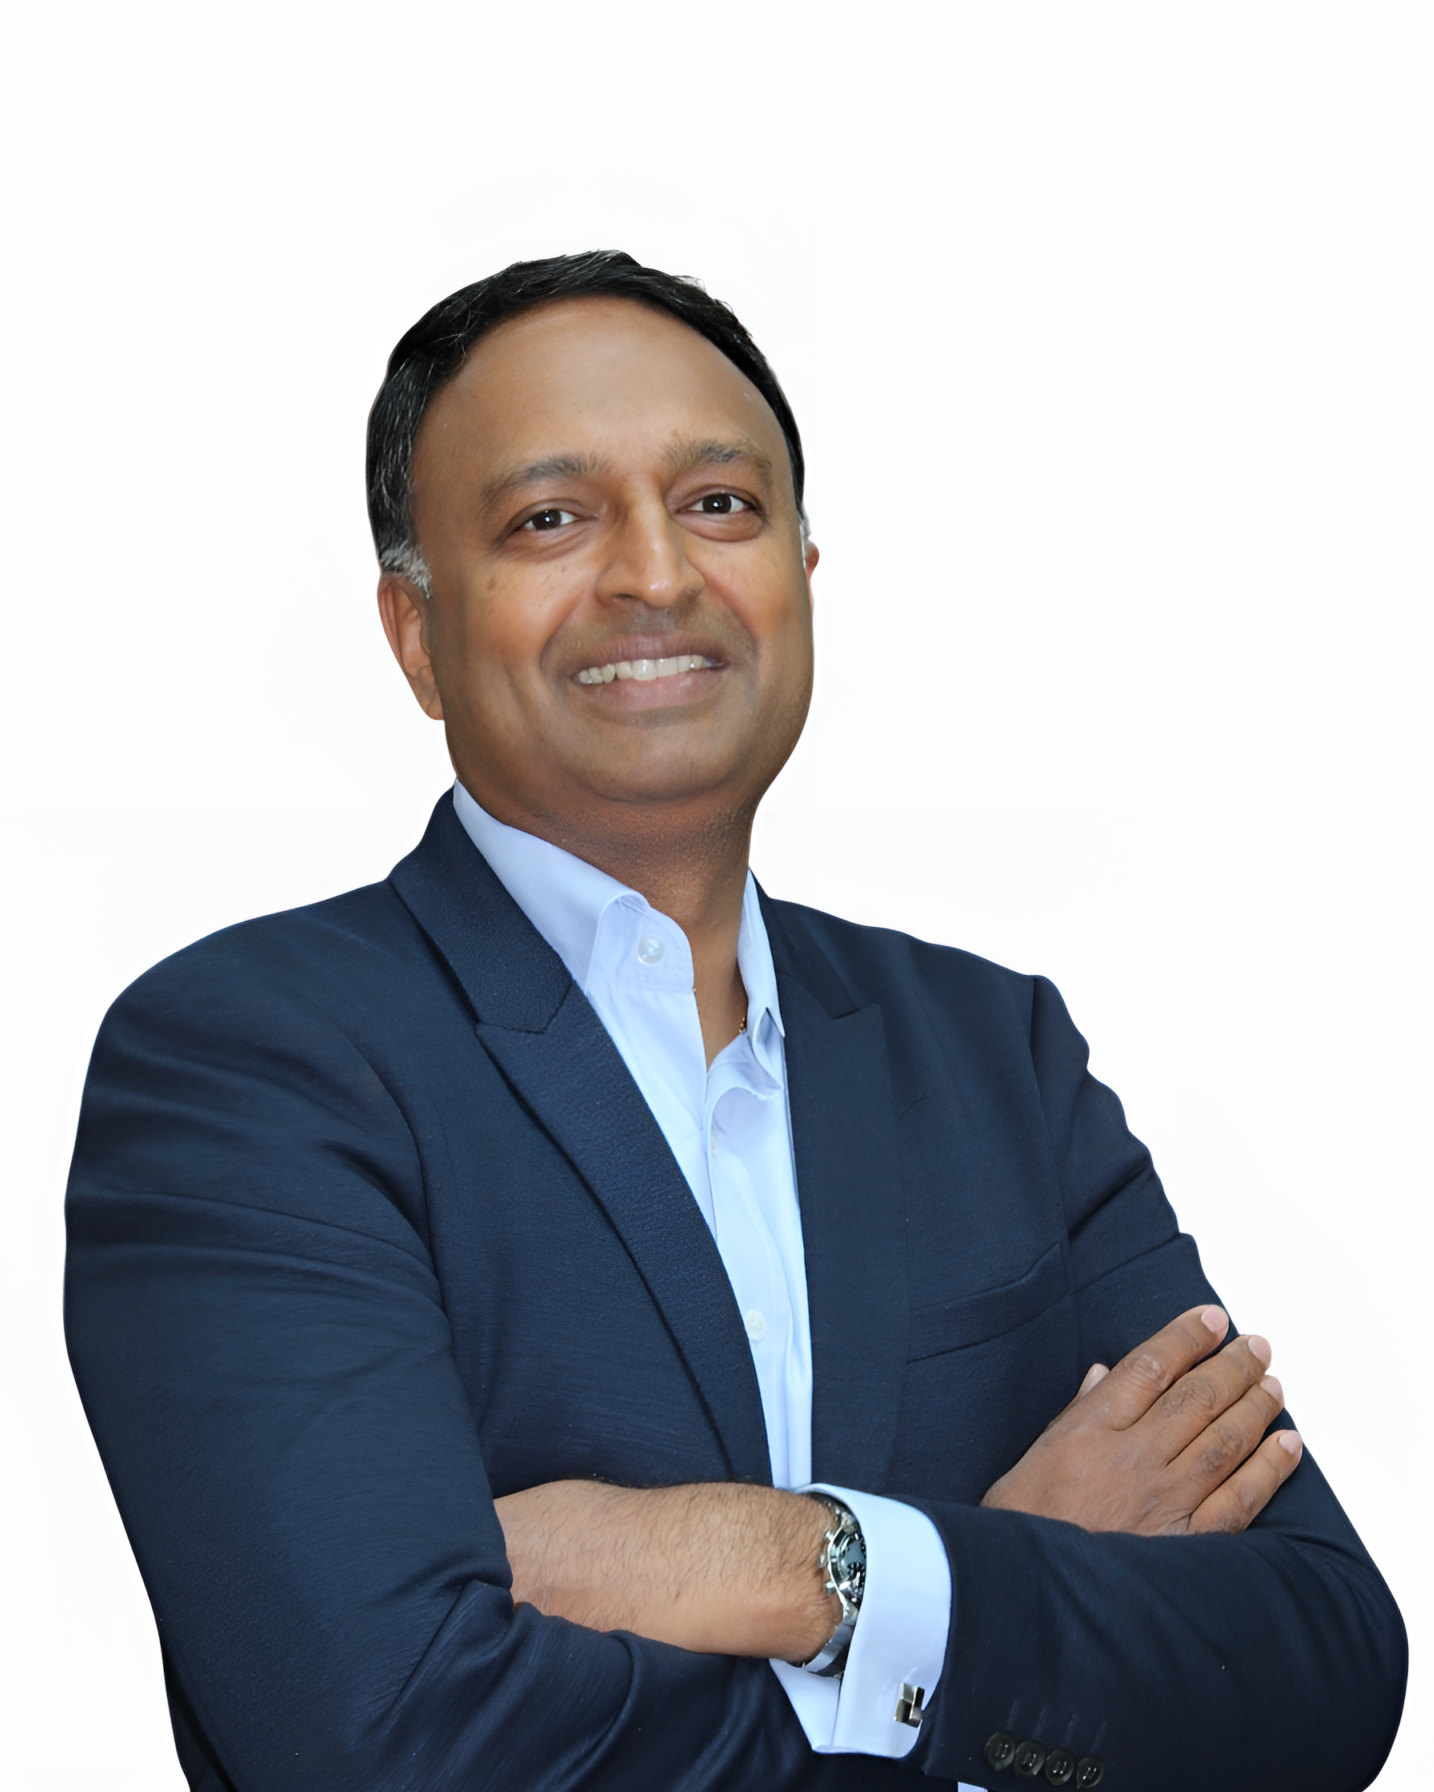
Ashendran Padayachee | Head | Legal and Compliance | Momentum | mail me |
South Africa’s financial system holds an estimated R88 billion belonging to people who don’t know they’re owed money. Forgotten retirement fund payouts, dormant bank accounts, unpaid insurance proceeds, and unclaimed investment returns make up much of this money.
In many cases, people have become untraceable after changing jobs, moving house, changing surnames, or passing away. Their beneficiaries were never told what they were owed.
Who should be trusted to find the rightful owners?
National Treasury recently published a discussion paper proposing a solution: a single, centralised system to help South Africans find and claim that money. Rather than having each bank, insurer, retirement fund, and investment provider run its own separate tracing process, a central administrator would hold one consolidated database. It would coordinate tracing efforts, run a single public-facing claims portal, and process valid claims on behalf of financial institutions across the industry.
The financial institutions would transfer the unclaimed assets into safe custody with the Corporation for Public Deposits. However, the assets would remain, in law, the property of their rightful owners. Meanwhile, a central body would take on the administrative burden of finding those owners.
The plan is deliberately incremental. It would start with unclaimed retirement fund benefits before eventually expanding to banking, insurance, and investment products. Treasury has also floated the idea that claims could eventually expire. This could happen either 45 years after an asset became payable or once the owner has turned 110. The proposal aims to give the system a practical endpoint. However, it raises questions about an individual’s ongoing right to money that is legally theirs.
The paper poses eight formal questions to industry stakeholders, with written comments already due on 19 September. It is, by design, an early-stage document rather than a finished blueprint. Instead, it sets out a direction for the proposed system. The responses it receives will shape how, and whether, this idea moves forward.
An industry perspective
We have been involved in the industry debate around the proposal. He explains that unclaimed benefits are linked in part to the quality of member data on hand. Incomplete employer records and cross-border migration also contribute to the problem. In addition, the industry faces a broader challenge in maintaining up-to-date client contact details over time.
As a financial institution, we often talk about a cradle-to-grave product and service methodology without necessarily focusing on client data to support that methodology over a product’s full lifecycle.
Does Treasury’s paper accurately reflect the reality of tracing beneficiaries in South Africa? The country has its own unique mix of informal settlements, incomplete records, and mobile populations.
National Treasury has drawn extensively from international experience. South Africa does face challenges that may differ somewhat from what is ostensibly international best practice. On balance, I regard the paper as a reasonable starting point. I believe it can initiate a broader industry debate on the reunification of unclaimed benefits.
Is centralisation the right answer?
Perhaps the most substantial question the paper raises is whether a single centralised administrator is actually necessary to solve the problem. Alternatively, could the same outcomes come from raising standards across the existing, decentralised system?
I am not convinced by the case for centralisation as it currently stands. A system of common standards applied consistently across existing administrators – effectively levelling the playing field – could offer many of the same benefits with less disruption, lower setup costs, and greater speed to implementation. There is also operational risk in concentrating data and process in one place that magnifies cyber risk, platform failure, and governance risk.
Centralising the management of unclaimed benefits and the operationalisation of such a model should not divert attention from the core focus. Ultimately, that focus is the reunification of unclaimed assets in a way that demonstrably improves on existing models. This will be the litmus test for the proposed model.
The paper suggests that an asset would cease to be claimable after 45 years from the date it became payable to the owner. Alternatively, it could cease to be claimable when the owner reaches 110. Padayachee believes the proposed age thresholds for classifying benefits as unclaimed require further consideration. This would allow policymakers to account for legal considerations around the potential curtailment of ownership rights and its consequences.
At the same time, he is cautious about applying the uniform 24-month definition of “unclaimed” under the Pension Funds Act across the industry. Financial products differ in terms of contractual triggers and ownership arrangements.
The elephant in the room
If the state plans to consolidate R88 billion of other people’s money into a single, government-linked custodial structure, it is reasonable to ask whether the institutions responsible for holding and safeguarding that money have earned that level of confidence. These institutions would also become responsible for tracking down the rightful owners.
South Africa’s recent history with governance and accountability at state-affiliated entities has been, at best, uneven. Consequently, many South Africans may feel cautious about handing large pools of capital to a new centralised body, however well-intentioned.
This isn’t necessarily an argument against reform. Nor is it a claim that private administrators are inherently more virtuous than public ones. Private institutions carry their own risks, incentives, and failures. They are also not above scrutiny.
Nevertheless, it is a legitimate question that deserves an honest answer as part of this process. Does centralising R88 billion in unclaimed money under a single administrator genuinely solve the tracing and data problems Treasury has identified? Or does it simply relocate risk from a fragmented private-sector system to a concentrated, government-linked one? It could do so without necessarily improving accountability along the way.
Given the scale of the money involved, Treasury and the public need to consider this question seriously. They should not assume that centralisation is automatically the safer or better option.
What happens next
The coming weeks will determine how much of this proposal survives industry and public scrutiny in its current form. Whatever the outcome, the underlying problem remains. Billions of Rands are sitting unclaimed, while a system has struggled for years to reunite that money with its rightful owners.
In other words, the R88 billion unclaimed money problem isn’t going away on its own. The debate about the right way to fix it, however, is only just getting started.